AI Inference Stocks: The Post-Training Opportunity
AI inference stocks are the companies positioned for the phase of AI that comes after the model is built: running trained models at “speed and scale,” in the presenter’s phrase, to answer real requests in real time. The category has become the hottest contention point in AI investing because of a simple economic truth: training a model is a one-time project, but serving it is a forever cost that scales with usage. This article explains the inference opportunity, who the players are, and how Brown’s “One Stock Retirement Plan” pitch fits into it. We walk through the specifics in our The Only AI Stock You Need to Retire: Jeff Brown’s Case piece.
Why inference is the next spending wave
Every AI product you use is an inference bill. When ChatGPT writes an email or a coding assistant autocompletes a function, compute is consumed per request, forever. As AI moves from chatbots to autonomous agents that act continuously, inference demand compounds: usage grows on its own once products ship, while training spend is episodic. Brown, the former Qualcomm and NXP senior executive who publishes The Near Future Report, frames it as the dial-up-to-broadband transition: “Dial up was ‘slow internet’… Broadband was ‘fast internet’… And the companies that made that transition possible made their shareholders incredibly wealthy.”
His thesis names: “Most of the investments in AI so far have focused on what I call ‘generic AI.’ And Nvidia was the big beneficiary of that first phase. But the future will be powered by what I call ‘Accelerated AI.’”
The technical bottleneck: latency
The engineering problem inference stocks are solving is latency. Models are too big for one chip, so they are split across many, and the chips constantly exchange data, each exchange adding delay. Brown’s classroom analogy: “It’s like trying to pass a note down a long row of people sitting in a classroom. Every single person who has to take the note and hand it to the next one adds a little delay… That’s called latency in a computing system.” For real-time products, a coding agent, live security analysis, instant customer service, latency is the product: slow answers mean no product, no matter how smart the model.
The players, mapped
The incumbent: Nvidia (NVDA). The default inference platform today, with the CUDA software moat and annual chip cadence. Nvidia is not conceding inference; every generation targets it directly. Owning the whole AI stack, training plus inference, is why its revenue keeps surprising.
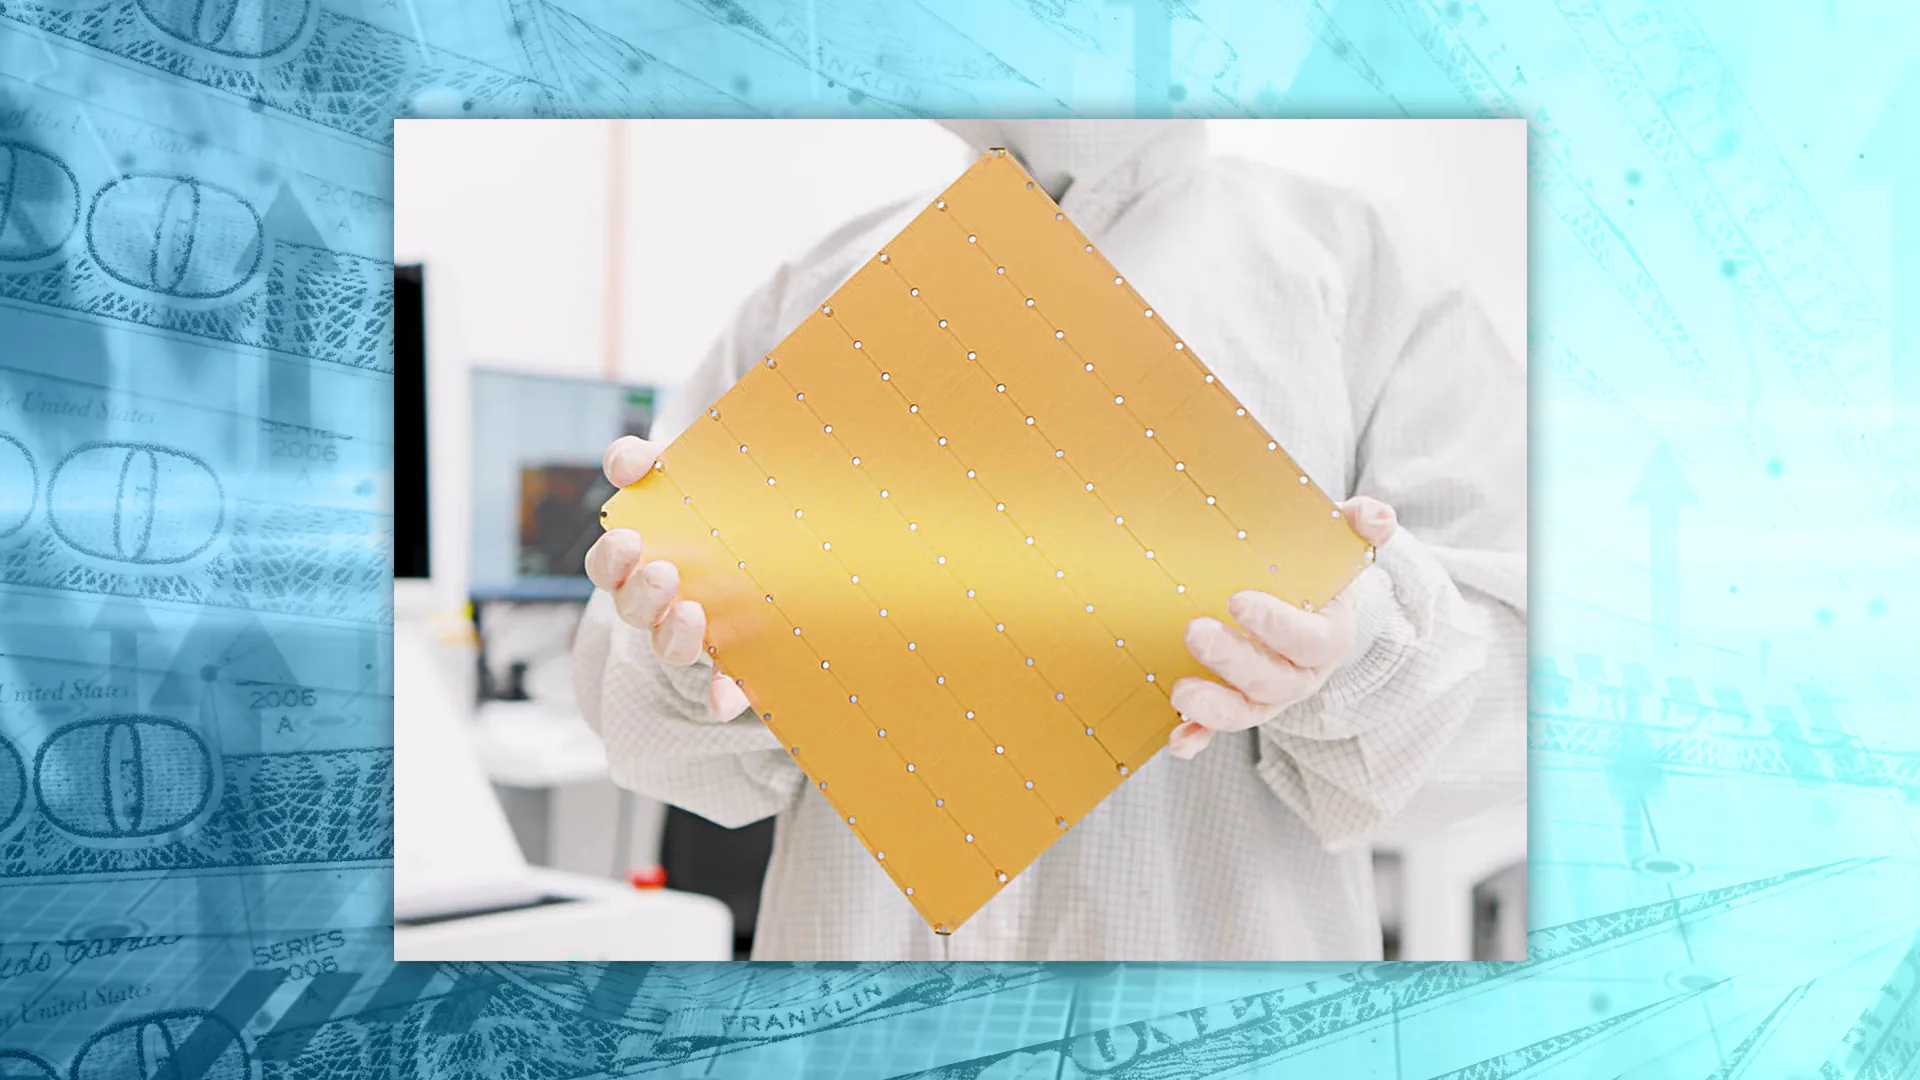
The challengers. Purpose-built inference architectures attack latency differently. The company Brown teases, which our clue analysis matches to Cerebras (CBRS), builds wafer-scale chips that collapse an entire cluster onto one piece of silicon, eliminating most inter-chip hops. The pitch’s numbers: “150 patents,” “a $24 billion backlog,” “sold out into 2027,” sales growth “about 500% a year since 2022… almost six times faster than Nvidia’s current sales growth,” and partners including OpenAI, Microsoft, IBM, AMD, Amazon, CrowdStrike, and GlaxoSmithKline. AMD’s Instinct line and the hyperscalers’ custom silicon (Google’s TPUs, Amazon’s Trainium) are the other challengers, contesting inference from different directions.
The enablers. Networking and interconnect companies (Broadcom, Astera Labs, Credo), memory suppliers, and edge-chip makers (the names in our Ambient AI edge stocks piece) all sell into the inference buildout regardless of which compute architecture wins.
The catalyst framing in the pitch
Brown ties his timing to Elon Musk’s infrastructure: Terafab, the $119 billion Texas chip plant documented in a Texas government filing, and Starmind, the FCC-noticed plan for “up to one million AI satellites.” More compute of any kind, his logic runs, means more inference, and the near catalyst is an Amazon/AWS deployment he expects to be detailed “on an important call with Wall Street analysts,” framed against a “before November 11” date. The buildouts are real; the date is marketing urgency around real catalysts.
Considerations
The category’s honest risks: the “1,000 times FASTER” claims in the pitch are the presenter’s characterization of an architectural advantage, not verified benchmarks; the competitive race is three-sided and live; and inference-optimized names, being newer, trade with more volatility and teaser-driven attention cycles. Brown’s own disclosure is the right anchor: The Near Future Report averages a 39.4% gain since inception, against peak picks like Nvidia at 4,100%, and his hedge, “I’m not recommending folks put their entire savings in this one stock,” is the posture every inference investor should copy.
Where to learn more
Brown’s specific pick and ticker are in “The One-Stock Retirement Plan,” included with a $179 trial of The Near Future Report, backed by a 30-day keep-everything refund guarantee. For background, read our review of Brown’s 10X Project pitch, the Near Future Report profile, and our the presenter presenter profile. For the technical distinction, our training vs inference explainer covers the same shift from another publisher’s angle.
NewsletterVetter is an independent publication. We receive compensation from some of the services we review through affiliate links. Nothing on this site is investment advice. Always do your own research.